3 Fraud Prevention Strategies for Your Business

Internal theft in business is all too common. Search the internet and you will find many articles about embezzlement by trusted employees. 


The good news: There are steps you can take to safeguard yourself and your company without relying on ‘trust’ as a method of prevention.


Reduce the risk of fraud in your business by following these three steps.

1. Establish Internal Controls 

One of the easiest ways to protect yourself against fraud is to have processes in place so no one person has access to your accounts. Creating a process in which there are at least two signatures or approvals on every check or expenditure can help. 


There are electronic systems that can assist you in tracking this approval process and provide tiers of approval. For example, if there is a bill over $5,000, you can require the head of the department to approve it, in addition to the two other approvers.


You should also perform unannounced audits on the system. When you do this, you can catch issues early or deter them entirely—it’s harder to embezzle money when the system is reviewed unexpectedly. 


One of the biggest issues we encounter involves sharing usernames and passwords. Please do not give anyone full access to your accounts. This includes bank accounts, credit cards, and your accounting system. There are permission levels for all these accounts to keep you and your company safe.

2. Establish Separation of Duties

This principle is the basis of a solid internal control system. It involves dividing the responsibility of a process between two or more people. 


For example, the person who collects checks from clients should not be the same person who deposits those checks. The person who reconciles the bank statement should not be the same person who approves payments. And the person who runs payroll should not be on payroll (they should not be paying themselves).

3. Utilize Outsourcing

One of the most effective ways to reduce your risk of fraud is to outsource your bookkeeping and accounting to an experienced company. This provider will be able to create internal controls and have a road map for separation of duties, which will eliminate the risks involved. They will have processes in place to review your transactions, ask questions, and ensure oversight on others in the accounting system.


Implementing fraud prevention strategies now will not only help you control the situation, but it will also save you time and money in the future.

Our Latest Insight

By Alisa McCabe September 21, 2026
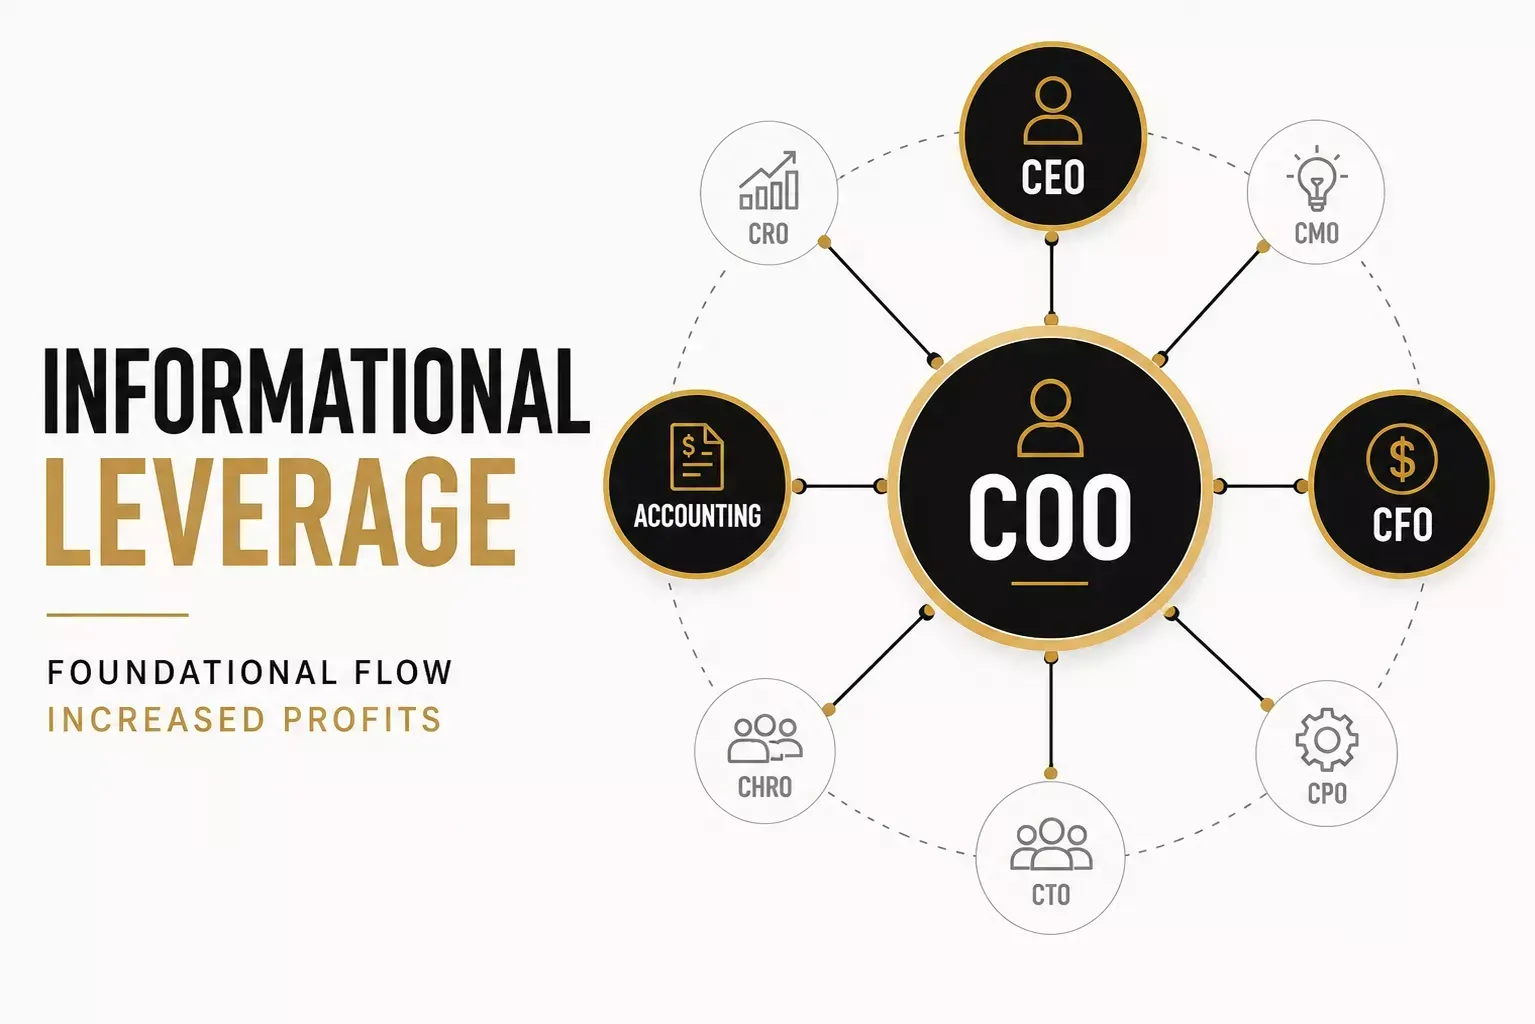
Article 1 ended with a question. When does your COO actually talk to Accounting before a decision gets made? How long did it take you to answer? Immediately? Minutes? Maybe you could not think of a single example. Bills get paid, projects keep moving, and financial reports show up. Nothing feels obviously broken, so you conclude everything is fine. If that question made you uncomfortable, you are not alone. Here is the part that keeps this problem alive. You only know what good looks like based on what you have already lived through. Most owners have never worked inside a business where Operations and Accounting were intentionally built to function together. So they measure their company against their own status quo. This article gives you a different reference point. You will see what the relationship looks like day to day, what rhythm it runs on, and five things you can check this week. None of it requires scrapping what you have built. The people are already in the building. The data already exists. What changes is how the pieces are arranged, and how much leverage you get out of the company you have right now.  ​ Part 2 of a 5-part series on the COO-Accounting relationship
By Alisa McCabe September 14, 2026
"Accounting is a stick in the mud." "I'm not really sure what a COO does all day." "The CFO just plays around with their little Excel sheets." You have probably heard one of those lines. You may have thought one yourself. They sound like harmless office humor. They actually point to something expensive. In most growing service businesses, nobody has ever defined how operations and accounting work together. The people who produce your financial reports sit outside the very decisions those reports are meant to inform. That gap costs you every single month, quietly, in profit that should have been there.  ​ Part 1 of a 5-part series on the COO and Accounting relationship
By Alisa McCabe September 14, 2026
In modern business management, effective capacity planning requires far more than matching supply with demand—it demands a rigorous financial framework. Every unit of unused capacity represents sunk cost and margin erosion, while every unit of insufficient capacity risks churn and missed revenue. By evaluating capacity planning as a financial exercise, organizations can translate labor hours, utilization rates, and operational throughput into clear financial metrics like cost of goods sold (COGS) and return on invested capital (ROIC). This guide explores how to integrate operational capacity into your financial planning and analysis (FP&A) cycle to drive sustainable, cash-efficient scale.

CONTACT US

Contact Us