Blog
There is a frustrating stage of growth when the business makes more money and becomes harder to run. You expected growth to create leverage. Instead, your calendar is fuller and decisions take longer. Projects compete for the same people. Expenses become harder to explain. Accounting needs more information from Operations. Operations needs more information from Accounting. And the accounting systems that carried you to $2 million were not built for $15 million. Nothing necessarily looks broken. That is what makes this stage so deceptive. The processes that got you here may still work. Your people may still be good. Your customers may still be buying. What changed is the weight your existing structure is being asked to carry. At $2 million, you can still personally compensate for the gaps. Somewhere on the road to $5 million, $10 million, or $15 million, that stops being possible. The business did not suddenly become dysfunctional. It outgrew its dependence on informal coordination. Part 5 of a 5-part series on the COO-Accounting relationship
If Article 3 felt a little too familiar, your first instinct may be to call a meeting. You tell Operations and Accounting they need to communicate better. That will not fix it. The five warning signs were never personality problems. They were signs that your accounting systems and routines were never intentionally built around how these two functions work together. People cannot follow a structure that does not exist. Accounting cannot inform decisions they do not know are being considered. Your COO cannot use financial information they cannot access in time. The fix is not complicated. That does not mean it happens naturally. Most of what you need to build will feel almost obvious. Recurring conversations. Clear handoffs. Shared definitions. Access to the right information. This is not glamorous work. That is probably one reason it gets overlooked. For the first few months, you may have to follow up constantly. People will forget. Meetings will get moved. Someone will make a decision and skip the handoff. Then something starts to change. The follow-up becomes unnecessary. Information moves without you. Problems get caught earlier. Eventually the results look effortless from the outside. They were not. You built the relationship that made them possible. Part 4 of a 5-part series on the COO-Accounting relationship
Article 2 ended with a question. What would you actually see first if this relationship started breaking down inside your business? Here is the answer. You would see five things. If you are like most owners reading this, you are already looking at two or three of them. None of the five announces itself as a communication problem. Each one shows up as friction inside your accounting systems, wearing a perfectly reasonable disguise. That is the difficulty. On the surface, none of these looks like a broken relationship. Each looks like something else entirely. A busy month. A tough quarter. A personality difference between two people who were never going to be friends anyway. Every one of them gets explained away the first time you see it. That is exactly what makes them expensive. This article does not fix any of it. Article 4 does that. The job here is naming what is already sitting in front of you. Most owners walk past these signs for years without recognizing what they are looking at. Part 3 of a 5-part series on the COO-Accounting relationship
Article 1 ended with a question. When does your COO actually talk to Accounting before a decision gets made? How long did it take you to answer? Immediately? Minutes? Maybe you could not think of a single example. Bills get paid, projects keep moving, and financial reports show up. Nothing feels obviously broken, so you conclude everything is fine. If that question made you uncomfortable, you are not alone. Here is the part that keeps this problem alive. You only know what good looks like based on what you have already lived through. Most owners have never worked inside a business where Operations and Accounting were intentionally built to function together. So they measure their company against their own status quo. This article gives you a different reference point. You will see what the relationship looks like day to day, what rhythm it runs on, and five things you can check this week. None of it requires scrapping what you have built. The people are already in the building. The data already exists. What changes is how the pieces are arranged, and how much leverage you get out of the company you have right now. Part 2 of a 5-part series on the COO-Accounting relationship
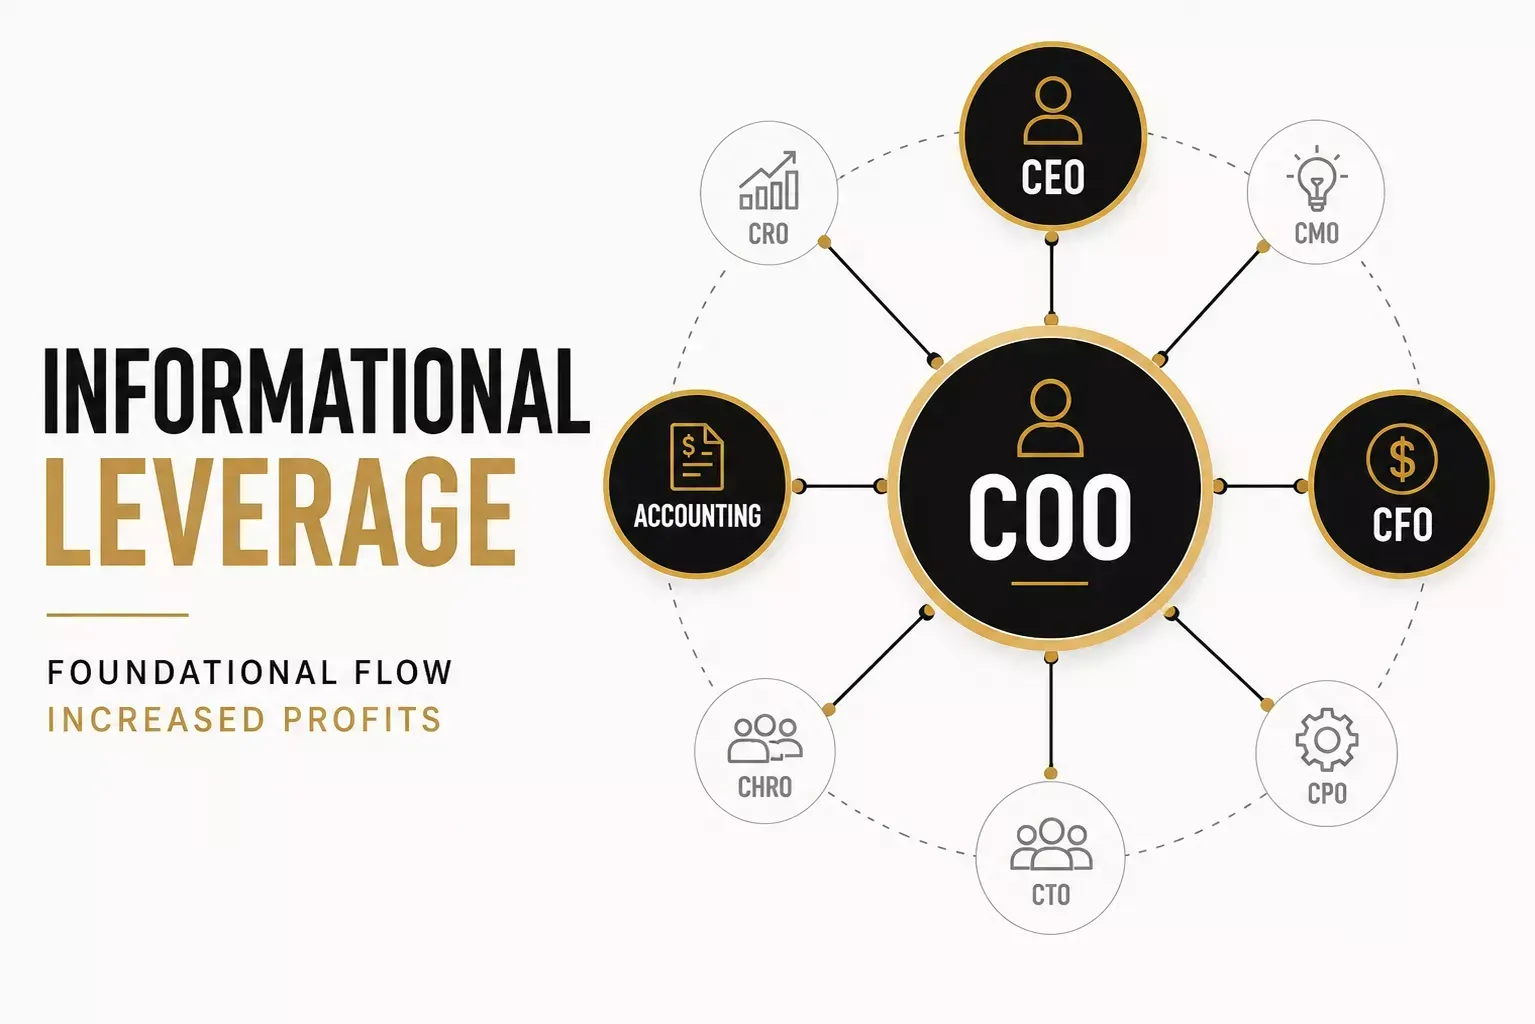
"Accounting is a stick in the mud." "I'm not really sure what a COO does all day." "The CFO just plays around with their little Excel sheets." You have probably heard one of those lines. You may have thought one yourself. They sound like harmless office humor. They actually point to something expensive. In most growing service businesses, nobody has ever defined how operations and accounting work together. The people who produce your financial reports sit outside the very decisions those reports are meant to inform. That gap costs you every single month, quietly, in profit that should have been there. Part 1 of a 5-part series on the COO and Accounting relationship
In modern business management, effective capacity planning requires far more than matching supply with demand—it demands a rigorous financial framework. Every unit of unused capacity represents sunk cost and margin erosion, while every unit of insufficient capacity risks churn and missed revenue. By evaluating capacity planning as a financial exercise, organizations can translate labor hours, utilization rates, and operational throughput into clear financial metrics like cost of goods sold (COGS) and return on invested capital (ROIC). This guide explores how to integrate operational capacity into your financial planning and analysis (FP&A) cycle to drive sustainable, cash-efficient scale.
In a service-based business, time is literally money, and every day an invoice goes unpaid, your margin shrinks. Unlike product businesses that can rely on physical inventory to back up value, service providers face a unique cash flow vulnerability: you've already delivered the work, paid your team, and covered overhead long before the client settles the bill. That makes managing your Accounts Receivable (AR) aging schedule critical to survival. But how do you know if your outstanding invoices are normal or a sign of trouble? Understanding key AR aging benchmarks, and where your service business stands relative to industry standards, is the first step toward reclaiming your cash flow and protecting your bottom line.This article walks you through the 30-60-90 AR Health Check and what healthy numbers look like for your business.
Between tracking fluctuating material costs, managing subcontractor fees, and juggling multiple active jobs, contractors face a unique set of financial complexities. At the heart of keeping these moving parts organized is the Chart of Accounts (COA), the foundational index of every financial transaction your business makes. For a contracting business, a well-structured COA does far more than just keep the tax preparer happy. It serves as the backbone for accurate job costing, allowing you to see exactly which projects are driving profits and which ones are eating into your margins. This article will guide you through the essentials of building a specialized Chart of Accounts tailored specifically for contractors, highlighting the unique categories you need to track, and sharing best practices to streamline your bookkeeping and elevate your business insights.
Fractional accounting gives your business a bookkeeper and controller for a flat monthly fee. Below you will find what it covers, what it costs, and how to know if it fits.
In the contracting world, where projects can span months or even years, managing cash flow and financial reporting is a unique challenge. Unlike traditional businesses that recognize revenue at the point of sale, contractors must choose how and when to account for their income and expenses. Two of the most common frameworks used to navigate this are Progress Billing (often paired with the Percentage of Completion Method ) and the Completed Contract Method (CCM). Progress Billing allows contractors to invoice clients and recognize revenue incrementally as milestones are met throughout the project. Completed Contract Method defers all revenue and expense recognition until the entire project is officially finished. Selecting the right method goes far beyond basic bookkeeping; it fundamentally shapes your tax obligations, cash flow health, and how creditworthy your business appears to lenders and investors. This article breaks down the core differences between these two methods, explores their pros and cons, and helps you determine which strategy is the best fit for your business.
Choosing new software can overwhelm any accountant. The options feel endless, and each one costs real time and money to test. Building the right accounting tech stack takes years of trial and error. We know, because we have spent over a decade doing exactly that. Our firm has been fully remote since 2012. That means we have tested, rejected, and adopted these tools inside real client work. Here is the stack we trust, so you can skip the guessing. You will notice we left AI off this list. We use it where it helps, but that is a topic for another day.
In the construction industry, managing cash flow presents significant hurdles, and the nuances of work deposits often lead to underestimated complications. Mastering construction accounting entails a precise grasp of how these upfront funds navigate your ledger, the timing for revenue recognition, and the strategies to prevent financial pitfalls that could jeopardize your business. For any contracting firm, proper deposit accounting is a necessity rather than an option. The accuracy of your financial statements, job costing, and overall cash liquidity depends entirely on it.